
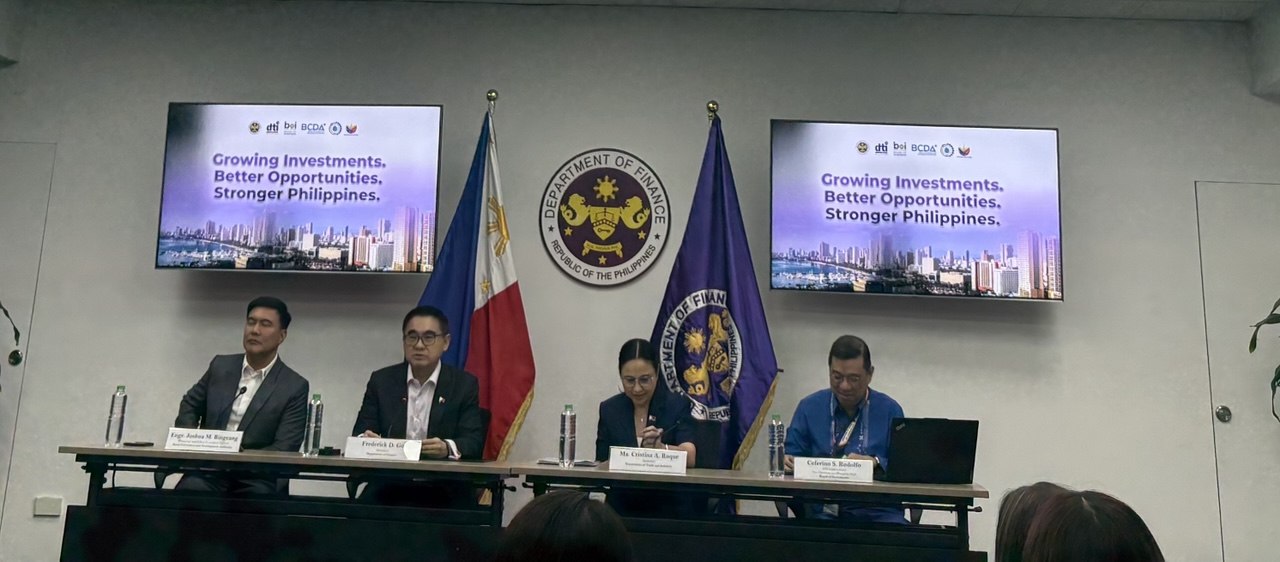
Approved investments of the Philippines’ three largest investment promotion agencies rose 39 percent to P1.4 trillion in January to October 2026, with the Board of Investments accounting for nearly two-thirds of the increase.
Figures presented at a briefing showed combined approvals of the BOI, Philippine Economic Zone Authority and Bases Conversion and Development Authority reached P1.398 trillion from P1.006 trillion a year earlier—an increase of P391.9 billion.
Finance Secretary and economic and investment czar Frederick Go said the government would work to translate the approvals into operating businesses, employment and revenues.
“These approvals are real gains because every investment brings an entire ecosystem of employers, workers, suppliers, and service providers,” Go said.
BOI approvals increased 22.3
percent to P942.86 billion from P770.71 billion, contributing P172.15 billion to the overall gain.
PEZA approvals climbed 77 percent to P309.63 billion from ap175.37 billion, exceeding its P300-billion full-year target.
BCDA recorded the fastest growth at 143 percent, with approvals reaching ap145.46 billion from ap59.98 billion.
BOI Managing Head Ceferino Rodolfo said the agency had achieved about 94 percent of its P1-trillion annual target, with renewable energy accounting for 79 percent of approvals. He expressed confidence that BOI would surpass its target before year-end.
Trade Secretary Cristina Roque said PEZA projects would expand manufacturing capacity, support exports and create quality jobs.
BCDA President and CEO Joshua Bingcang meanwhile cited prospective investments in agriculture, energy and aviation facilities.
Go said the government’s next task was to move projects “from approval to execution” and opening, so their benefits would make a meaningful difference in the lives of Filipino families.