
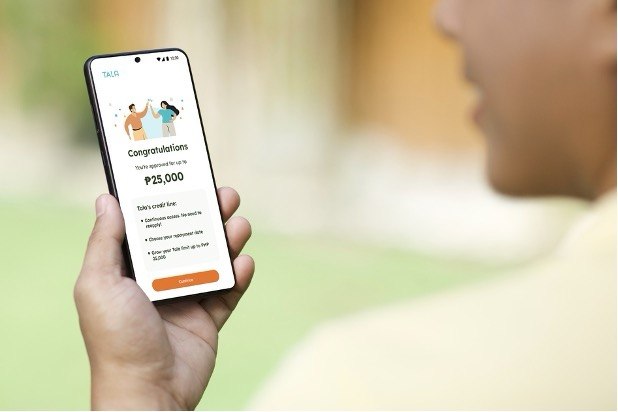
Tala Philippines is expanding partnerships with financial institutions, payment networks and businesses to widen credit access, as the fintech company looks beyond traditional lending channels to reach borrowers underserved by banks.
The company is promoting its Credit-as-a-Service (CaaS) platform, which allows businesses to integrate Tala’s credit assessment technology into their own applications and customer networks. The expansion comes as only 58% of Filipino adults own formal financial accounts, according to figures cited by Tala.
Through application programming interfaces and software development kits, partner companies can offer credit using Tala’s alternative-data scoring technology, with lending decisions delivered within minutes. The approach targets borrowers with limited conventional credit histories, including small entrepreneurs and economically active Filipinos who may have difficulty qualifying for traditional bank loans.
“Financial inclusion thrives when different parts of the ecosystem work together,” said Moritz Gastl, president and general manager of Tala Philippines.
Under the partnership model, Tala provides credit decisioning technology and risk intelligence, while its partners contribute capital, distribution networks and access to customers. The company is also expanding loan-channeling arrangements with financial institutions to secure additional funding and potentially reduce borrowing costs.
Tala’s disbursement network includes banks, electronic wallets and over-the-counter payment channels, allowing customers to receive funds through digital and cash-based options.
The strategy reflects a wider push by financial technology companies to use partnerships to extend lending beyond established banking networks. However, expanding access does not automatically translate into affordable credit, particularly for borrowers with limited financial resources.
Tala is also emphasizing consumer safeguards through industry collaboration, anti-fraud initiatives and its Debt with Dignity advocacy against abusive collection practices.
The expansion’s broader impact will depend on whether increased lending reach translates into responsible borrowing, manageable repayment obligations and sustained access to formal financial services for underserved Filipinos.