
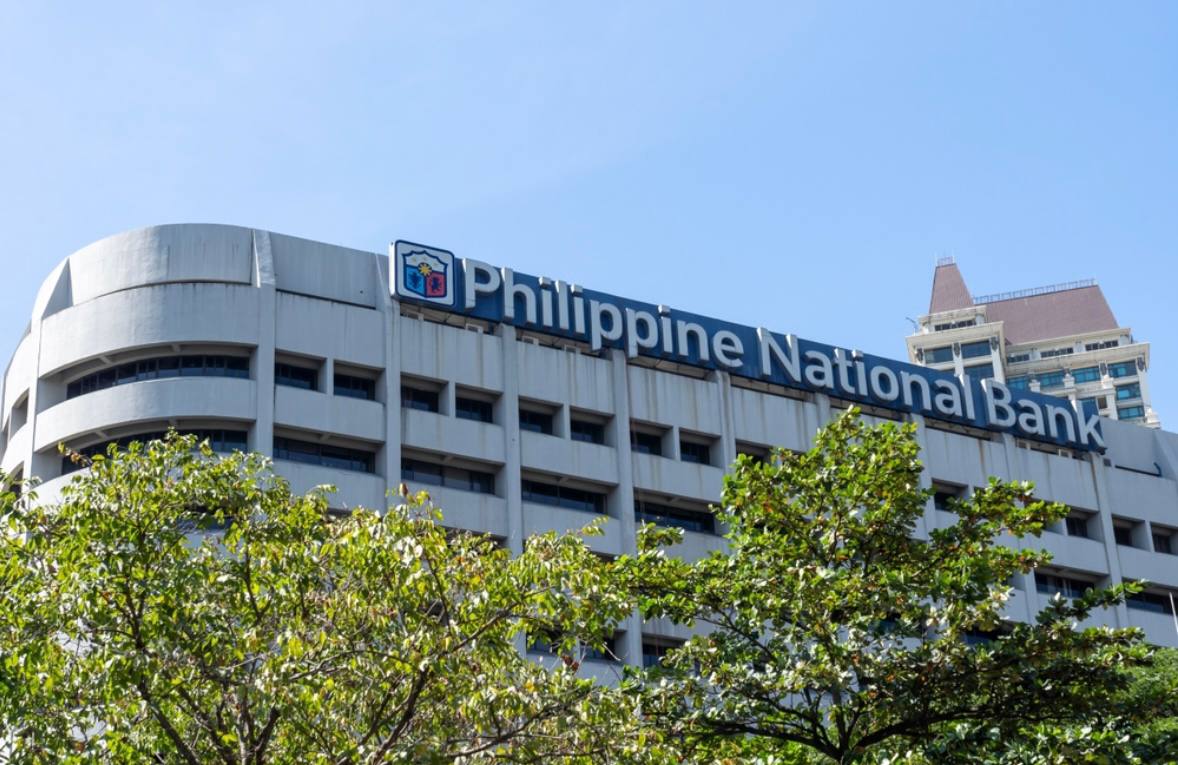
The Philippine National Bank (PNB) recorded a net income of ₱21.3 billion for the nine months ended September 30, 2026, marking a 15 percent increase from ₱18.5 billion during the same period last year. The performance underscores the bank’s disciplined execution, expanding core operations, and strengthening capital base as it drives long-term value creation.
The financial metrics reflect robust operational health and enhanced profitability. Return on equity improved to 11.6 percent from 11.0 percent year-on-year, while return on assets rose to 2.1 percent from 2.0 percent. Total deposits expanded by 9 percent, supported by a healthy low-cost deposit base where current and savings account (CASA) deposits comprised 78 percent of total deposits. This stable funding foundation, paired with prudent loan pricing, enabled the bank to maintain a net interest margin of 4.6 percent.
Lending operations demonstrated broad expansion across key sectors. Gross loans increased 13 percent year-on-year to reach ₱793 billion. Corporate and commercial loans grew 15 percent to ₱726 billion, while consumer loans rose 11 percent to ₱66 billion, with mortgage loans driving over 80 percent of consumer portfolio growth.
Asset quality showed substantial improvement alongside credit expansion. The gross non-performing loan (NPL) ratio dropped to 4.0 percent from 5.2 percent a year earlier, driven by active collection efforts, resolution of non-performing accounts, and stronger credit quality in newly booked loans.
Diversified revenue streams further bolstered earnings during the period. Non-interest income was boosted by growth in fee-based services, particularly bancassurance and credit card fees from the PAL Mabuhay partnership. Notably, Allianz-PNB Life secured the top position in the 2026 New Business Bancassurance Industry Ranking.
Leadership emphasized the strategic significance of these results. President and Chief Executive Officer Edwin R. Bautista highlighted that the nine-month results and improving asset quality demonstrate disciplined execution, while artificial intelligence initiatives are starting to yield tangible benefits. Chief Financial Officer Francis B. Albalate added that the successful listing of PNB Holdings Corporation will allow the bank to realize the full economic value of its investment, further reinforcing its capital base and long-term prospects.
Philippine National Bank maintains a solid financial position, reporting a Common Equity Tier 1 (CET1) ratio of 19.3 percent and a Capital Adequacy Ratio (CAR) of 20.0 percent, both well above regulatory requirements. Backed by strong capital, improving asset quality, and ongoing investments in digital technology, the institution remains well-positioned to serve evolving customer needs and pursue sustainable growth.